Four | Buy Now, Pay Later

Screenshots
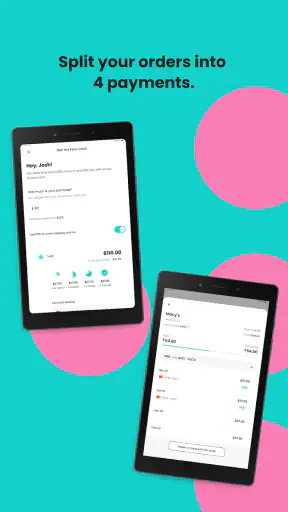
Details
- Rating
- 5.44K reviews
- Version
- 1.17.84
- Developer
- Four Technologies, Inc
Analysis by Norviv
Four | Buy Now, Pay Later is the kind of shopping app I would approach with a clear plan rather than casual curiosity. Its purpose is simple: it lets me shop online and spread a purchase across flexible payments. That can be useful when an essential item arrives at an inconvenient moment, but it also means I need to understand the payment schedule before I confirm anything. The app is free to download, aimed at Everyone, and belongs to the shopping category.
After spending time with it, my main impression is that Four is less about browsing for entertainment and more about changing how I handle a checkout. The value appears at the moment I decide whether one purchase should be paid all at once or managed over time. That makes the app potentially helpful for planned spending, while making it a poor fit for anyone who wants an effortless way to buy things without checking their budget.
Where the experience can become confusing
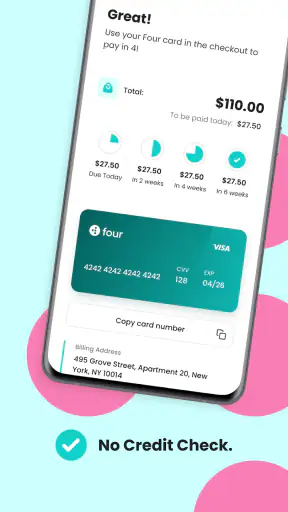
The first point where I would expect users to get stuck is not necessarily the shopping itself. It is understanding how the payment option fits into the checkout flow. A “buy now, pay later” service can feel different from an ordinary card payment because the purchase and the repayment arrangement are connected. I would slow down at the final confirmation screen and read every displayed amount, date, and condition before continuing.
That extra pause matters because a flexible payment plan can make an individual purchase look more manageable while still creating several future commitments. I would not judge affordability by the first amount alone. Instead, I would look at the total cost and consider whether the later payments will overlap with rent, subscriptions, travel, or other planned expenses.
Another possible source of friction is the difference between the app and the retailer’s own checkout. Four is a shopping payment tool, not necessarily the entire store experience. If a product page loads normally but the payment option does not appear, that does not automatically mean the app is broken. The retailer, product, order value, account status, or checkout method may affect what is offered at that moment.
I also found that this type of service rewards careful timing. If I open it while trying to make a rushed purchase, I am more likely to miss an important detail. My better routine is to decide what I need first, confirm the seller and final basket total, and only then consider whether splitting the payment is sensible.
The app has built a substantial audience, with more than a million installs and an average rating of 4.4 from roughly thirteen thousand ratings. Those figures suggest that many people find the idea useful, but they do not remove the need for personal checking. A popular payment app can still be unsuitable for someone who prefers one immediate transaction or who finds recurring commitments difficult to track.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
What I check before starting a purchase
Before using Four, I make sure the account details I enter are accurate and consistent with the information used at checkout. Small mismatches can create avoidable delays, especially when a payment service needs to identify the customer or connect the purchase to the right order. I also check that the shopping cart is final rather than assuming I can change the item later without affecting the payment arrangement.
My second check is practical: I confirm that the device can run the app. Four currently lists Android support from version 6.0 onward, so compatibility should be broad on Android phones that are still maintained. I would nevertheless keep the operating system and the app updated where possible. The current app version is 1.17.84, and using an older build can make troubleshooting harder if a checkout screen behaves unexpectedly.
Four was released on January 22, 2021, by Four Technologies, Inc. I mention that because it helps place the app in context: this is an established shopping service rather than a brand-new experiment, but its behavior can still depend on the surrounding retailer checkout and the device environment.
Before confirming a plan, I would also check the available balance on the card or account connected to the first payment. A failed initial charge can interrupt the order even when the overall purchase looks affordable. If I am using a phone with several payment or shopping apps installed, I close anything unnecessary and return to Four from a clean session. That is a simple step, but it helps separate an app problem from a browser or checkout handoff problem.
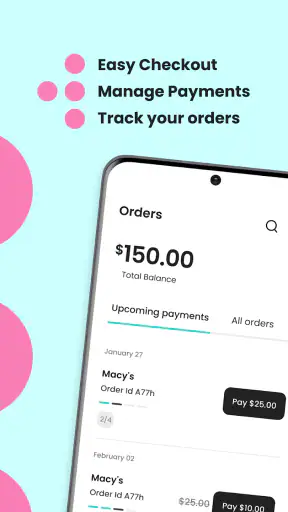
One useful habit is to take note of the order total and the repayment dates shown during confirmation, without relying on memory. I do not treat a notification as my only reminder. A personal calendar entry or budget note makes it easier to see how the purchase fits alongside other commitments. This is especially useful when I make more than one purchase in a short period, because several individually small plans can become difficult to follow together.
How I recover when checkout does not go through
When a purchase fails, I avoid repeatedly pressing the confirmation button. First I check whether the order actually went through by looking for an order confirmation from the retailer and reviewing the purchase area available to me. Repeating the attempt too quickly can create uncertainty about whether there are duplicate pending transactions, even if the retailer eventually processes only one.
If there is no completed order, I restart with the basics: stable internet access, the latest available app version, enough device storage, and a fully restarted app. I also retry from the retailer’s checkout rather than assuming that reopening Four alone will recreate the same session. This distinction is important because the problem may be in the handoff between the store and the payment service.
For a payment that appears pending, I give the transaction time to update instead of immediately starting another purchase. I compare the retailer’s order status with the payment status shown in the app and keep any confirmation details. If the two sides disagree, those details are more useful when contacting support than a general message saying that “it did not work.”
I would not uninstall the app as the first troubleshooting step. Removing it can erase a convenient local session and make it harder to tell whether the original attempt is still being processed. A better order is to refresh the session, check the account and order information, restart the device if necessary, and then contact the appropriate support channel if the status remains unclear.
There is also a practical recovery rule for declined transactions: do not immediately assume that changing the item or trying several cards will solve everything. Check the displayed reason or instruction first, then review the cart and payment details. If the purchase is urgent, paying through a familiar alternative may be more sensible than spending a long time forcing one payment method to work.
This is one of the app’s important trade-offs. Four can make a checkout more flexible, but it adds another layer to a purchase. A regular debit or credit card is usually simpler when I want one transaction and no separate repayment tracking. A traditional budgeting app is better when my main goal is planning cash flow rather than choosing a payment option at checkout. Four is most useful when its payment structure solves a specific short-term problem and I am comfortable managing the follow-up.
When the app is not the cause
It is easy to blame the payment app when a purchase is unavailable, but the retailer may be the real source of the limitation. A store can change its checkout, remove a payment method, restrict certain products, or experience an outage. If Four works normally elsewhere while one retailer fails, I would investigate the store’s checkout before changing phone settings or reinstalling anything.
The same applies to a product that disappears from the cart or a total that changes unexpectedly. Shipping, taxes, discounts, stock, and seller rules are generally controlled by the retailer. Four can only work with the information passed into the payment stage. I would compare the final amount shown by the store with the amount shown before confirming the payment plan, because that is where an unexpected difference becomes visible.
Network problems can also imitate an account or payment problem. A weak connection may leave a page half-loaded, while a private network configuration or temporary browser issue may prevent a checkout handoff. My safe approach is to switch to a reliable connection, reopen the retailer’s checkout, and avoid making a second attempt until I know whether the first one completed.
Device settings can play a role too. An outdated operating system, aggressive battery management, insufficient storage, or a blocked browser handoff can interfere with any shopping app. I do not change security settings blindly. Instead, I update the phone, restart it, confirm that Four is allowed to operate normally, and test the same checkout in a straightforward environment.
There is a more personal cause that deserves attention: the payment may be technically available but financially unsuitable. If I need to keep checking whether I can cover the next scheduled amount, the convenience is no longer helping me. In that situation, an ordinary payment method or waiting until the purchase fits my budget is the better choice. The app should support a plan I already understand, not persuade me to stretch beyond it.
The Everyone age rating makes the app broadly accessible from a content perspective, but that should not be confused with financial suitability for every shopper. I would involve a parent or responsible adult when appropriate and make sure the person using the payment arrangement understands the commitment. Accessibility of an app does not turn deferred payment into free money.
A realistic way I would use Four
Imagine that I need a replacement household item after an unexpected failure. I find the product, check the seller, confirm the complete order total, and compare the payment schedule with my next few weeks of expenses. If the future amounts fit comfortably and I understand the arrangement, Four gives me an option beyond paying the full amount immediately.
I would then save the order details and add reminders for the scheduled payments. I would not use the app to add unrelated accessories simply because each extra item looks inexpensive on its own. The strongest use case is a defined purchase with a clear need, a known total, and a repayment plan that remains manageable even if another ordinary expense appears.
For planned shopping, I would prepare outside the checkout. I might keep a short list of the items I actually need, set a maximum total, and decide in advance whether splitting the cost is worthwhile. This reduces the chance that the convenience of Four changes my shopping decision after I have already committed time to browsing.
For returns or order changes, I would start with the retailer because the retailer controls the product, shipment, and order process. I would also keep an eye on the payment status rather than assuming that a returned item automatically settles every related payment instantly. Connecting the store’s return confirmation with the payment record gives me a clearer trail if something needs follow-up.
Who should use it, and who should skip it?
I think Four is a good match for shoppers who often buy online, want a flexible way to manage a planned purchase, and are willing to monitor the resulting payments. It may also suit someone who dislikes opening a separate spreadsheet for every purchase but still wants to see the payment arrangement before confirming an order.
I would recommend skipping it if the main attraction is simply being able to buy something that is currently outside the budget. I would also choose a standard card or direct payment when the purchase is small enough to pay comfortably at once. The extra payment layer is not automatically an advantage; sometimes simplicity is the real benefit.
People who frequently lose track of subscriptions, forget due dates, or have unpredictable income should be especially cautious. A flexible checkout option can be useful, but it cannot remove the underlying obligation. If tracking several future payments already feels stressful, adding another service may create more work than it saves.
Compared with ordinary cards, Four’s appeal is the payment arrangement at checkout. Compared with a bank’s financing option, it may feel more directly connected to online shopping. Compared with shopping apps that focus on product discovery, its purpose is narrower and more practical. I prefer that focus, but it also means I would not install it expecting a complete marketplace, price-comparison tool, or personal finance system.
My practical verdict after using it
Four | Buy Now, Pay Later is a focused shopping app that can make an online purchase easier to organize when I have a genuine need and a repayment plan I can comfortably follow. I like the idea of deciding at checkout rather than arranging a separate loan-style process, and the app’s free price makes trying the service straightforward.
My reservation is equally clear: the convenience can hide the amount of attention required afterward. I would read the final payment details, record the dates, verify the retailer’s order status, and avoid repeating a failed checkout until I know what happened. Those habits are not optional extras; they are what make the app safer and less frustrating to use.
With a current version of 1.17.84 and support beginning at Android 6.0, the technical entry point is accessible to many Android users. The rating of 4.4 and a review count of around five thousand four hundred show a generally positive reception, but my recommendation remains conditional rather than automatic.
My bottom line is simple: use Four for a deliberate purchase, not as permission to spend ahead of your means. If you want flexible checkout payments and are prepared to track what follows, it is worth considering. If you want the fewest moving parts, a normal card or direct payment will usually be the cleaner choice.
Frequently Asked Questions
01What is Four, and how does its buy now, pay later service work?
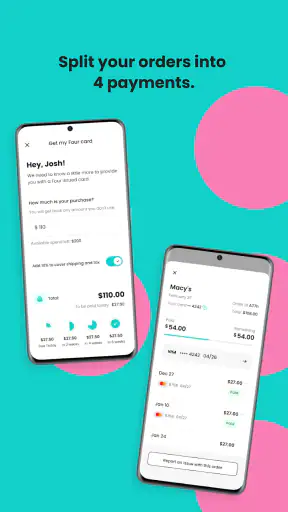
Four is a buy now, pay later service that allows eligible shoppers to split the cost of a purchase into multiple scheduled payments instead of paying the full amount immediately. After selecting Four at checkout, the app or merchant typically shows the payment schedule before you confirm. Approval, available payment plans, and purchase limits can vary depending on your account, order value, and other eligibility checks.
02Does Four charge interest, fees, or a down payment?
Four commonly advertises installment plans with no traditional interest when payments are made according to the agreed schedule, but the exact terms can differ by merchant, plan, and location. Some purchases may require an initial payment, while late, returned, or unsuccessful payments could result in fees or account restrictions. Always review the final checkout summary, including payment dates and any applicable charges, before accepting the plan.
03What information is required to sign up for Four?
To use Four, you generally need to provide personal and payment information, such as your name, contact details, date of birth, and a valid debit or credit card. Four may also perform an eligibility or identity check before approving a transaction. Approval is not guaranteed, and the information requested can vary based on local regulations, the merchant, and the value of the purchase.
04Can I use Four for every online or in-store purchase?
Four is only available at participating merchants and for products or transactions that meet its conditions. Certain categories, order amounts, subscriptions, gift cards, or other restricted purchases may not qualify. Availability can also depend on your location, account status, and the payment method connected to your profile. Look for Four during checkout or in the app’s merchant directory before planning to use it.
05What happens if I miss a Four payment or need to return my purchase?
If a scheduled payment fails or is missed, Four may retry the payment, apply a fee where permitted, restrict future use, or take other action described in its terms. If you return an item, you normally need to follow the merchant’s return policy first; the merchant must process the refund before Four can update or cancel the remaining installment balance. Continue checking your payment schedule until the return is fully confirmed.


